Glossary
The words.
As the product uses them.
The words on the two dashboards, in the product's own wording. Where the two products use a word differently, both meanings are given.
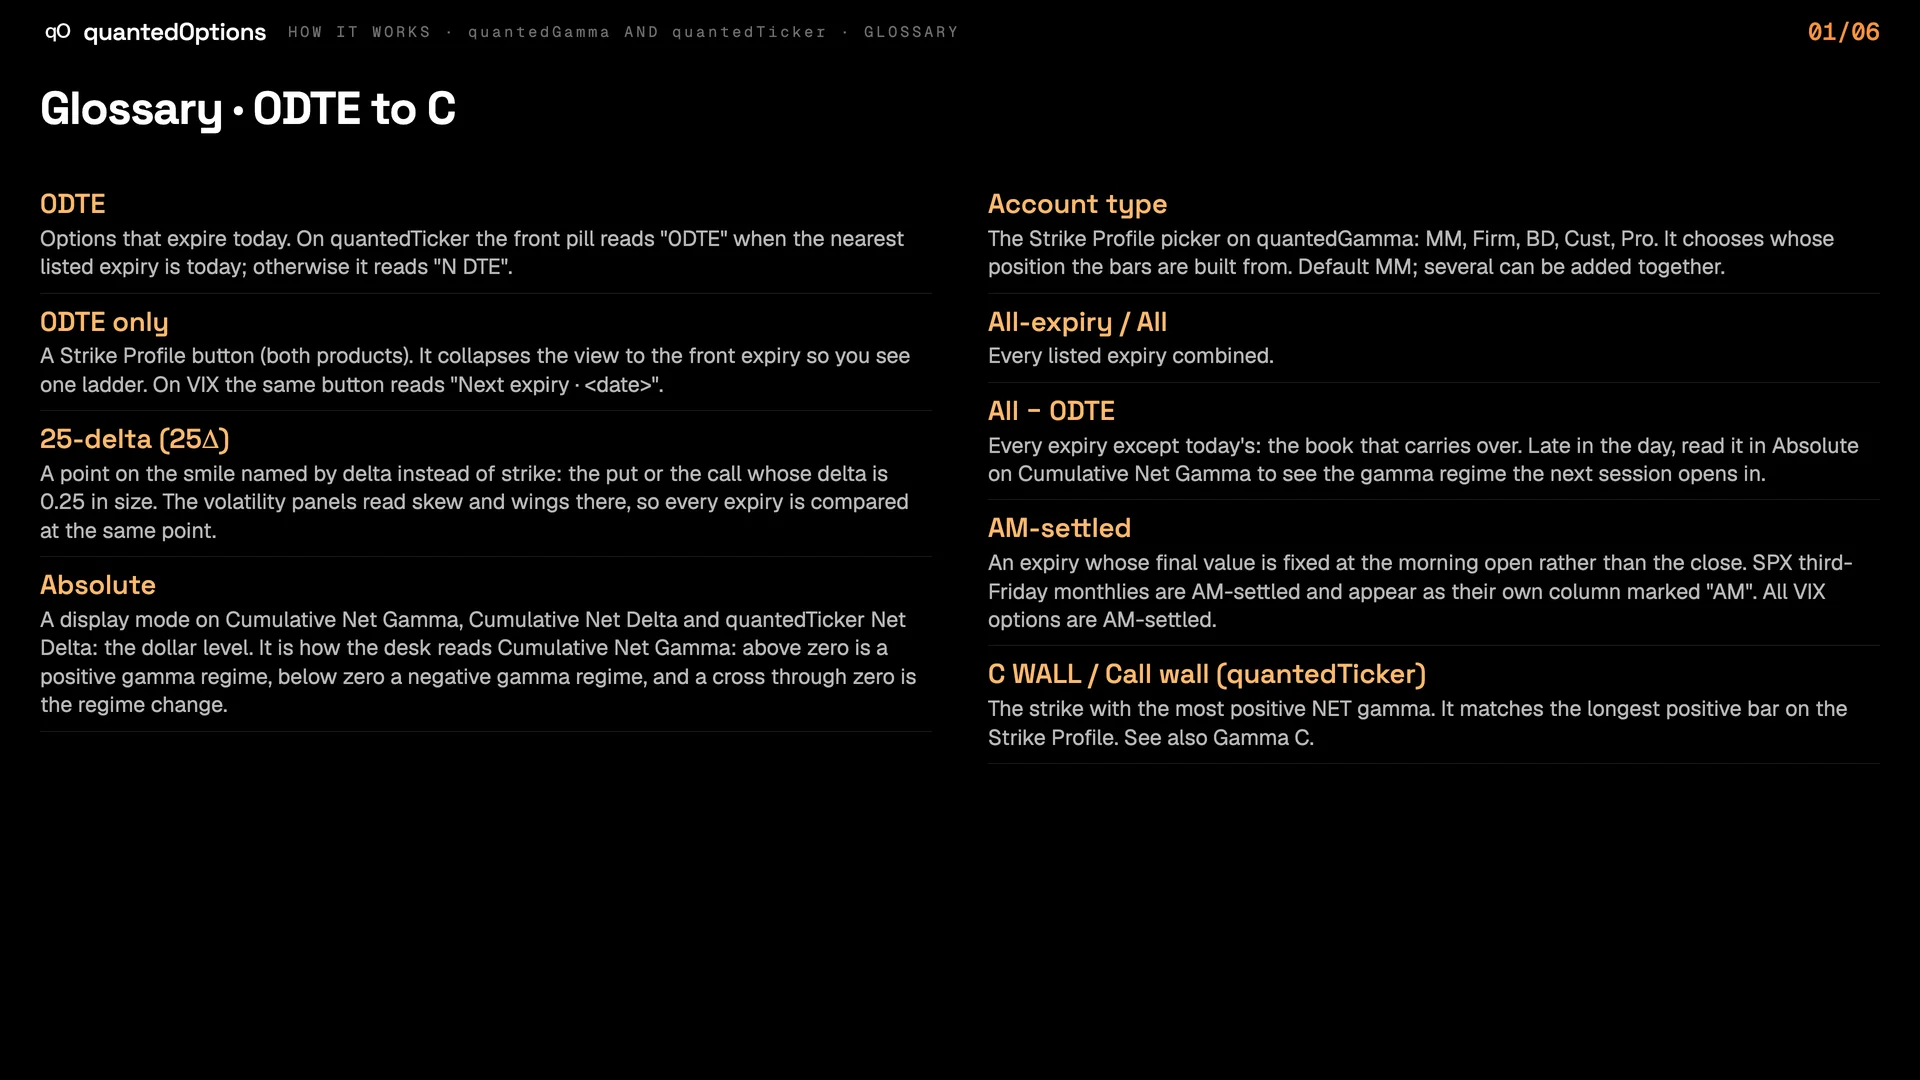
- 0DTE
- Options that expire today. On quantedTicker the front pill reads "0DTE" when the nearest listed expiry is today; otherwise it reads "N DTE".
- 0DTE only
- A Strike Profile button (both products). It collapses the view to the front expiry so you see one ladder. On VIX the same button reads "Next expiry · <date>".
- 25-delta (25Δ)
- A point on the smile named by delta instead of strike: the put or the call whose delta is 0.25 in size. The volatility panels read skew and wings there, so every expiry is compared at the same point.
- Absolute
- A display mode on Cumulative Net Gamma, Cumulative Net Delta and quantedTicker Net Delta: the dollar level. It is how the desk reads Cumulative Net Gamma: above zero is a positive gamma regime, below zero a negative gamma regime, and a cross through zero is the regime change.
- Account type
- The Strike Profile picker on quantedGamma: MM, Firm, BD, Cust, Pro. It chooses whose position the bars are built from. Default MM; several can be added together.
- All-expiry / All
- Every listed expiry combined.
- All − 0DTE
- Every expiry except today's: the book that carries over. Late in the day, read it in Absolute on Cumulative Net Gamma to see the gamma regime the next session opens in.
- AM-settled
- An expiry whose final value is fixed at the morning open rather than the close. SPX third-Friday monthlies are AM-settled and appear as their own column marked "AM". All VIX options are AM-settled.
- C WALL / Call wall (quantedTicker)
- The strike with the most positive NET gamma. It matches the longest positive bar on the Strike Profile. See also Gamma C.
- Charm (CEX)
- How much delta changes from the passage of time alone, in dollars of delta per day. quantedGamma: the market maker's delta. quantedTicker: the delta of the open interest at that strike. *Negative charm is supportive, positive charm is suppressive* ("Charm Is Wind").
- Charm zero line
- The white "Zero" contour on the Charm surface: the prices where charm exposure changes sign, drawn from the current minute forward.
- Cohort
- A set of expiries drawn as one line: 0DTE (today's book), All-expiry (the whole book), or All − 0DTE (the book that carries over).
- Cumulative Net Delta / Gamma
- The market maker's total delta (or gamma) across every strike, plotted minute by minute through the session. Cumulative Net Gamma is the regime line and sits in its own slot in the quantedGamma workflow.
- Demand
- A Strike Matrix mode on the volatility panels: each cell's IV change minus the normal change for the underlying's move and the time of day. Faded numbers are inside that expiry's everyday noise.
- DEX
- Delta exposure in dollars: how many dollars of the underlying the options behave like. quantedGamma: the market maker's. quantedTicker: built on open interest, calls positive and puts negative.
- Dominant strike
- The strike with the largest positive market-maker gamma on the board. In the case-study sessions it acted as the target and then the ceiling or floor.
- Expected move
- The move implied volatility prices, one standard deviation. For 30 days: IV30 × spot × √(30/365). The 0DTE priced tile gives it from the minute on screen to the 16:00 close.
- Flip (quantedTicker)
- The zero gamma level: the price at which the total gamma, worked out again as if the underlying were there, crosses zero; the crossing nearest the price is shown. Sessions before Sep 23, 2026 keep the older flip: where net gamma, added strike by strike from the bottom up, crosses zero.
- Focus / dual / triple layout
- quantedGamma layouts of one, two or three panels. The full list: focus, dual, triple, standard, mirrored standard, comparison, quad, carousel.
- Gamma C / Gamma P (quantedTicker)
- The strike with the most call gamma and the strike with the most put gamma. Call wall / Put wall use NET gamma instead.
- Gamma flip
- See Zero gamma line.
- GEX
- Gamma exposure in dollars per 1% move: how many dollars of delta change if the underlying moves 1%. quantedGamma: the market maker's gamma. quantedTicker: built on open interest, with call gamma counted positive and put gamma negative.
- Implied volatility (IV)
- The volatility an option's price implies, annualized, in percent. Higher IV means pricier options.
- IV Rank / IV Percentile
- Where IV30 sits in the history window. Rank: 0 at the window's lowest IV30, 100 at its highest. Percentile: the share of days in the window with a lower IV30.
- IV30
- At-the-money implied volatility at a constant 30 days.
- MM view
- The market maker's own side of a number. All quantedGamma exposures are in MM view, and Premium Flow is the market maker's book.
- Negative gamma
- quantedGamma: market makers are net short options; their hedging goes with the move, so price moves through ("faster and farther, both ways"). quantedTicker: put gamma outweighs call gamma across the open interest.
- Net gamma
- Gamma exposure totalled over a set of strikes. Positive = a positive gamma regime; negative = a negative gamma regime. On quantedTicker the tile is captioned "OI proxy, $ per 1% move".
- Normal / left over
- On the volatility panels, the normal change is what a number usually does by that time of day plus its usual reaction to the underlying's move; left over is the rest. Left over is coloured only outside its everyday band.
- Off open
- A display mode: each line is shown as its intraday change since the start of the session. On quantedTicker the start is 09:30 ET.
- OI / VOL (quantedTicker)
- Open interest (contracts open) and volume (contracts traded since the open) on the Strike Profile, calls counted positive and puts negative. Counts, not dollars; open interest refreshes overnight.
- OI proxy
- The caption on quantedTicker's Net gamma tile ("OI proxy, $ per 1% move"): gamma built on open interest, with call gamma counted positive and put gamma negative.
- P WALL / Put wall (quantedTicker)
- The strike with the most negative NET gamma. See also Gamma P.
- Positive gamma
- quantedGamma: market makers are net long options at that strike (or in aggregate); their hedging works against the move, so price slows or stops.
- Proximity effect
- Gamma is largest near the money and near expiry, so a strike's exposure grows as price approaches it and as the close approaches. It is why 0DTE gamma gets noisy into the close, and why All − 0DTE is the line to read then.
- Realized volatility
- How much the underlying actually moved, on the same annualized scale as IV. Realized 21d is close to close over the last 21 sessions; Intraday realized counts only moves inside the session.
- Replay
- Viewing a past minute or a past day. Scrub or play any minute of any stored session on the replay bar; every widget on the page follows.
- Smile
- Implied volatility across strikes for one expiry. The volatility panels draw it across delta, puts on the left and calls on the right, so every expiry spans the same width.
- Surface
- A heat map of market-maker exposure across price (vertical) and time (horizontal). Right of "now" is the current book projected forward through the day.
- Term structure
- At-the-money IV by expiry, nearest first. Longer-dated options usually carry higher IV; a front end above the back is called inverted.
- Vanna (VEX)
- The change in delta, in dollars, for a one-point rise in implied volatility. quantedGamma: the market maker's delta. quantedTicker: the delta of the open interest at that strike.
- Vertical
- A spread: adjacent strikes with opposite signs on the Strike Profile (for example +$9.9B at 7610 against −$6.9B at 7615). Use Call/Put mode to see the legs.
- Wings
- The 25-delta butterfly: the average of the 25-delta put and call IV minus at-the-money IV. Both tails against the middle.
- Zero gamma line / gamma flip
- The price where net gamma crosses zero. On quantedGamma it is the "zero gamma" label on the Gamma Profile and the white Zero contour on the Gamma surface. Crossing it is a regime change: "Brakes become a gas pedal."
6 slides
The glossary as slides
Slide 1 / 6
These pages describe what the displays show and what the data did on the sessions shown. They are not trading advice, and a past session is not a forecast of a future one.